Nepal’s New Payment Bill: Fintech Reforms, Wallet Protection & Global Integration

24th September 2026, Kathmandu
Explore how Nepal is transforming its digital financial ecosystem with the Payment and Settlement (First Amendment) Bill, 2083. Discover key updates including the fintech regulatory sandbox, global payment provider entries, strict consumer data privacy, 30-day wallet refund guarantees, and enhanced national payment switch integration.
Nepal’s New Payment Bill Fintech
As financial technology (fintech) evolves at an unprecedented pace, Nepal is taking a major leap toward modernizing its financial ecosystem.
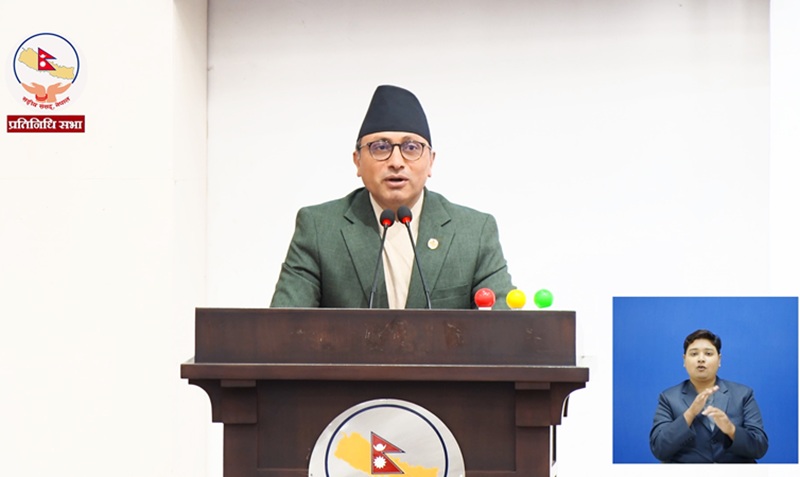
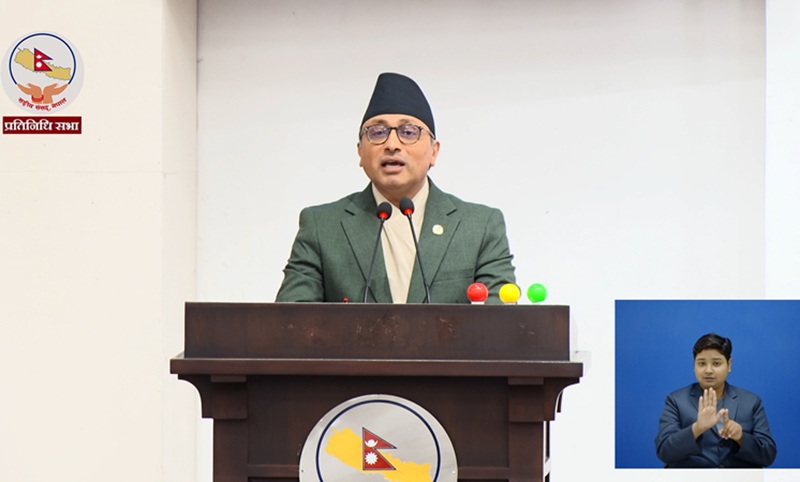
The House of Representatives has unanimously approved the Payment and Settlement (First Amendment) Bill, 2083, following a comprehensive theoretical discussion presented by Acting Prime Minister and Finance Minister Dr. Swarnim Wagle.
This landmark legislative update is designed to overhaul outdated legal frameworks, accommodate rapid fintech advancements, secure consumer data, and streamline international digital transactions in Nepal.

Why the Payment and Settlement Amendment is Crucial
While digital wallets and mobile banking have scaled rapidly across Nepal, existing laws struggled to keep pace with systemic liquidity risks, consumer data protection, and the potential entry of global payment giants.
The new bill acts as a core pillar in the government’s broader strategy to formalize and digitize the national economy, injecting transparency and legal safeguards into the digital transaction landscape.
Key Highlights and Provisions of the New Bill
Introduction of a Regulatory Sandbox: To foster financial innovation, the legislation introduces a Regulatory Sandbox concept. This legal mechanism allows the Nepal Rastra Bank (NRB) to grant time-bound and limited operational permits for startups and tech firms to experiment with cutting-edge fintech products.
Advertisement

Streamlined Entry for International Providers: Foreign payment service providers operating in at least 10 countries will be eligible to apply for operations in Nepal. The bill streamlines this process by removing mandatory on-site inspections for trusted, experienced international entities.
National Payment Switch Integration: To reinforce infrastructure management and corporate governance, all payment instruments and service institutions are now required to integrate directly with the National Payment Switch.
Stricter Consumer Data Privacy: Safeguarding customer data is a primary focus. The bill mandates strict confidentiality of customer logs, accounts, and personal details, capping how financial data can be shared with software vendors in compliance with NRB standards.
30-Day Wallet Refund Guarantee: In the event that a payment institution’s license is revoked or fails to renew, the legislation mandates that all remaining e-money balances in consumer wallets must be fully refunded within 30 days.
Enhanced Dispute Resolution & Legal Oversight: Major financial offenses under the Act will now fall under Schedule-1 of the Muluki Criminal Procedure Code as government-prosecuted cases. Furthermore, a 5-member Dispute Resolution Committee chaired by an NRB Deputy Governor has been provisioned to resolve commercial disputes between institutions within 15 days.
What’s Next for the Legislation?
During the parliamentary discussion, lawmakers emphasized balancing international integration with robust cybersecurity, capital flight prevention, and the protection of domestic firms. Finance Minister Wagle noted that the bill remains open to constructive amendments and will undergo detailed clause-by-clause reviews within the relevant parliamentary committee alongside industry experts and the central bank.
As these reforms take shape, Nepal is positioning itself for a safer, more competitive, and globally connected digital financial future.
For more: Nepal’s New Payment Bill Fintech